Will It Still Be There and When Should You Take It
“I will keep Social Security in a lockbox.”
– Al Gore
In 1940, a retired legal secretary named Ida May Fuller became the first person to receive a monthly Social Security check. She had paid a total of $24.75 into the system, and her first payment was for $22.54 – nearly her entire lifetime contribution returned in a single month. Over the years that followed, she collected benefits totaling $22,889 until her death at age 100 in 1975.
Social Security started out simple: Benefits began at age 65, payments were fixed, and a rapidly expanding workforce had relatively few retirees to support. Today, Social Security is far more complex, shaped by longer life expectancy, inflation adjustments, spousal coordination rules, income-based taxation, and a growing tension between promised benefits and long-term funding. Navigating the system now requires a level of planning and expertise that would have been unimaginable at its inception.
In the interest of brevity, we will focus on the two questions advisors hear most frequently: Will the system remain financially sound during my retirement? And when should I collect benefits?
A Challenge, Not A Collapse
Concerns about the solvency of Social Security are widespread. Politicians and the media warn that Social Security will be “insolvent by 2033”– a statement that is technically correct but misleading.
From the mid 1980s through roughly 2020, Social Security collected more in payroll taxes and interest than it paid in benefits. Those surpluses were credited to a trust fund and invested in Treasury securities, creating reserves to support the system when demographics inevitably shifted. That shift is here and, at the current rate of depletion, the surplus will be exhausted in 2033.
But depletion does not mean the program runs dry. Social Security is a pay as you go system – current workers’ payroll taxes fund the majority of benefits. So even if no action is taken, tax revenues are expected to cover about three quarters of scheduled benefits for decades to come.
If action is taken – which is likely – the adjustments need not be dramatic. A 2025 proposal from the Brookings Institution suggests that slight increases to 1) the payroll tax, 2) the retirement age for younger workers, and 3) the benefits tax for higher earners would maintain solvency for another 75 years. The Social Security system simply needs a tune-up.
When Can You Take Social Security?
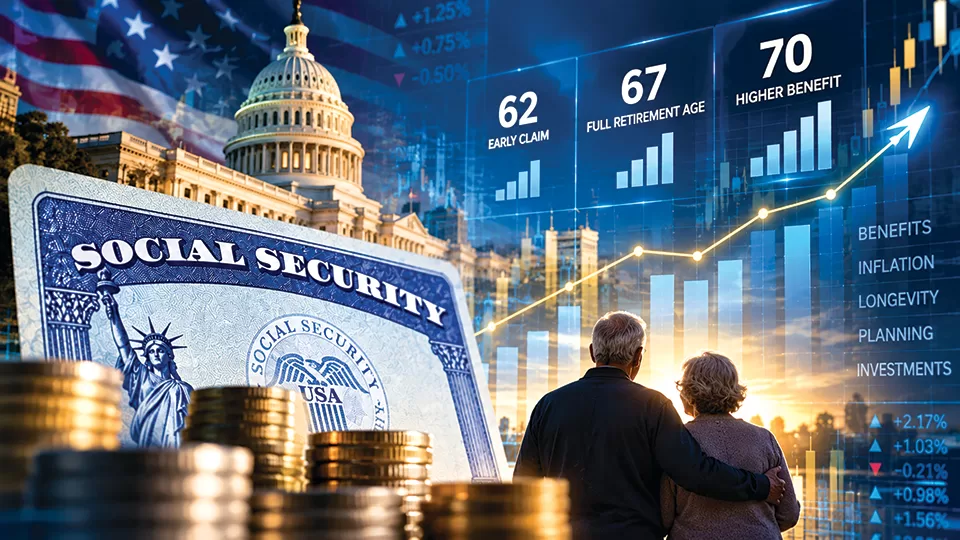
If you were born in 1960 or later, your Full Retirement Age is 67, when you receive 100% of your Social Security benefit. You can claim as early as 62, but your monthly benefit would be permanently reduced by about 30%. If you instead wait until 70, you receive about 124% of your full retirement amount. The trade-off is straightforward: take benefits at a younger age and receive smaller checks earlier, or wait and receive larger checks for the rest of your life.
For married couples, Social Security is a household decision. A spouse can usually receive the greater of his or her own benefit or 50% of the other spouse’s full retirement age benefit, which means spouses should coordinate when deciding when to file.
If action is taken – which is likely – the adjustments need not be dramatic. A 2025 proposal from the Brookings Institution suggests that slight increases to 1) the payroll tax, 2) the retirement age for younger workers, and 3) the benefits tax for higher earners would maintain solvency for another 75 years. The Social Security system simply needs a tune-up.
When Should You Take Social Security?
If you retire without another source of income, you may need to collect Social Security at 67 or even earlier. For many households, however, waiting is advantageous. If you have other assets – such as taxable investment accounts, retirement savings, or income-producing real estate – it is often beneficial to draw on those resources first and delay claiming Social Security.
By waiting, you reduce the risk that you may outlive your financial assets. Delaying benefits increases the guaranteed, inflation-adjusted income stream you will receive for the rest of your life. This is especially important for married couples who are planning not just for one person’s future, but for two.
According to Hal Hershfield’s The Behavioral Divide podcast, human psychology often pushes Social Security decisions in the wrong direction. After decades of contributing to the system, there is a natural inclination to begin collecting as soon as possible – “it’s my money and I want it now!” Loss aversion also comes into play: “What if something happens to me and I miss out on the money I am owed?”
At the same time, many individuals are reluctant to draw from their own retirement savings. There is a strong psychological aversion to spending down principal, even when those assets were accumulated specifically to support retirement. As a result, some retirees claim Social Security income earlier than is optimal, rather than using other retirement assets for their intended purpose. These behavioral tendencies are understandable, but they can work against your financial best interests. Social Security provides a lifetime, inflation-adjusted stream of income backed by the federal government. The larger the income stream, the more financially secure you will be later in retirement.
Finding The Right Answer For You
There is usually a “textbook” answer to the Social Security question, but it might not be your answer. While financial analysis can point toward an optimal strategy, you need to consider what feels right to you.
It may be helpful to reframe the question. Instead of asking what might go wrong if you wait until 70 to take Social Security, consider what might go right. Advances in healthcare, improved lifestyle choices, and family longevity all increase the probability of a longer life. It is entirely reasonable to plan for a retirement that extends well into your 90s, and delaying Social Security will pay off if you make it that far.
Social Security planning is inherently complex. The rules are nuanced, the trade-offs are real, and the optimal approach is highly dependent on individual circumstances. If you want to explore the topic further, the Social Security Administration’s planning tools can provide a useful foundation: www.ssa.gov/benefits/calculators/. Most important, have a discussion with your advisor to ensure your decision fits within your broader financial plan. This is an area where expert guidance can make a big difference.
By waiting, you reduce the risk that you may outlive your financial assets. Delaying benefits increases the guaranteed, inflation-adjusted income stream you will receive for the rest of your life. This is especially important for married couples who are planning not just for one person’s future, but for two.
According to Hal Hershfield’s The Behavioral Divide podcast, human psychology often pushes Social Security decisions in the wrong direction. After decades of contributing to the system, there is a natural inclination to begin collecting as soon as possible – “it’s my money and I want it now!” Loss aversion also comes into play: “What if something happens to me and I miss out on the money I am owed?”
At the same time, many individuals are reluctant to draw from their own retirement savings. There is a strong psychological aversion to spending down principal, even when those assets were accumulated specifically to support retirement. As a result, some retirees claim Social Security income earlier than is optimal, rather than using other retirement assets for their intended purpose. These behavioral tendencies are understandable, but they can work against your financial best interests. Social Security provides a lifetime, inflation-adjusted stream of income backed by the federal government. The larger the income stream, the more financially secure you will be later in retirement.